Hong Kong Finance Jobs Draw Returning Talent as Fundraising Rebounds

Hong Kong finance jobs are drawing renewed interest from professionals overseas as the city’s fundraising market gathers momentum. Recruiters interviewed by Reuters in a September 11 report described people returning from Singapore, London, Dubai and mainland China, with opportunities extending beyond investment banking into asset management, private wealth and family offices. It is a hiring story supported by stronger market activity, though not evidence that every part of finance is expanding equally.
The latest exchange figures help explain why employers are looking again. Hong Kong Exchanges and Clearing recorded 106 newly listed companies in the first eight months of 2026, compared with 59 during the same period last year. IPO fundraising reached HK$342.4 billion, while total equity funds raised reached HK$651.3 billion. The latter measure includes more than initial public offerings and should not be described as IPO proceeds alone.
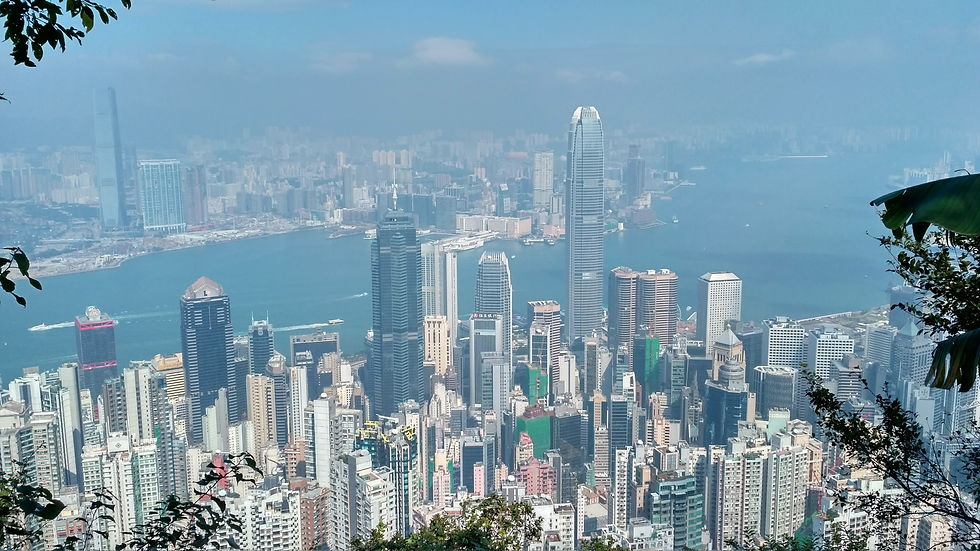
Central, Hong Kong, seen from Victoria Peak in 2016. Photo: Sebastiandoe5 / CC BY-SA 4.0. Display size adjusted.
Those are different signals of business activity. A new listing adds a company to the exchange, whereas a fundraising total measures the money raised through transactions. Neither is a direct count of job vacancies. Together, however, they provide a concrete backdrop to recruiters’ accounts of renewed demand: more financing activity means more transactions for firms to arrange, assess and support, even when staffing decisions remain selective.
Reuters reported demand not only for dealmaking staff but also for expertise in compliance, risk and the integration of artificial intelligence. That mix is important for professionals considering a move. A stronger market does not automatically create the same opportunity for every specialist. Employers may be hiring for a particular regulatory responsibility, client base or technical capability rather than adding people indiscriminately across an entire business.
The return of overseas professionals was visible before this week’s report. In August, The Standard reported that Robert Walters’ Hong Kong managing director, John Mullally, had observed a moderate increase in new roles for foreign professionals over the preceding six to 12 months. Investment banking and asset management were among the areas discussed, with both returning residents and people considering Hong Kong for the first time entering the picture.
That earlier account also emphasized careers rather than treating relocation as a simple tax calculation. For an individual, the relevant question is whether a specific employer can offer work and progression that justify a move. Family circumstances and the practicalities of living in another city remain part of that decision. Recruiter observations describe a change in interest and hiring conversations; they do not establish that every enquiry becomes an accepted job.
Caixin separately reported in August that the IPO revival and a proposed expansion of tax exemptions for fund managers were helping Hong Kong attract international finance talent. The distinction between a proposal and an enacted benefit matters. A recruitment decision based on anticipated policy should not be confused with a benefit already available on settled terms. The market recovery and the policy discussion are related influences, but they are not the same development.
Government investment-promotion figures offer another view of business confidence. In its June announcement, InvestHK said it had helped 413 mainland and overseas enterprises establish or expand operations in Hong Kong since the start of the year. Those projects were expected to bring more than HK$53 billion in direct investment and create more than 8,600 jobs. The figures describe expected investment and employment, not a verified tally of money already spent or people already hired.
They also cover a broader set of businesses than finance alone. Combining them with a banking recruitment report does not turn all of the projected jobs into financial-services positions. Their value is contextual: companies were committing to a presence in the city while recruiters were reporting renewed interest from professionals. Keeping the measures separate makes the recovery easier to assess without inflating either set of numbers.
For employers, the immediate issue is how to match recruitment to actual work. A busy fundraising period can support demand for transaction specialists, while wealth-management and compliance teams face different staffing needs. For candidates, a job title by itself reveals little about the client responsibilities, language requirements or experience an employer expects. The reports describe areas of activity, not a promise that an overseas applicant can move directly into them.
There are limits to what this evidence can establish. Recruiters see the parts of the market in which they operate, and announcements of investment projects look forward. Exchange statistics record completed market activity but do not measure the quality or durability of employment. None of these sources, individually, is a comprehensive census of professionals moving into and out of Hong Kong.
The strongest conclusion is narrower, and more useful, than a claim that the city’s comeback is complete. Hong Kong has a busier fundraising market, recruiters are seeing renewed demand in identifiable financial specialties, and some overseas professionals are responding. Whether that develops into a lasting expansion will become clearer through subsequent hiring, completed investment projects and further market activity—not through the enthusiasm surrounding a single strong reporting period.
Related coverage: Baidu's Hong Kong Dual-Primary Listing Deepens Its Commitment to the City.

Comments