Hong Kong’s New ETF Wave Is Turning Investment Themes Into a Product Race

HONG KONG — A cluster of exchange-traded funds began trading on the Hong Kong Stock Exchange on Wednesday, turning the city’s growing ETF market into a sharper competition over artificial intelligence, healthcare, income and cross-border growth. The listings include products from China Asset Management, Ping An and ICBC Credit Suisse, giving investors several new ways to buy a theme through one listed security.
The launch slate includes the ChinaAMC FTSE Hong Kong Growth ETF, ChinaAMC Hong Kong High Dividend ETF and ChinaAMC HK-US HALO ETF, alongside the Ping An AI Select ETF, Ping An Healthcare 50 Select ETF and ICBC UBS HK-Global Artificial Intelligence ETF. The concentration of products on one trading day is significant because it shows managers competing not merely on access to a market, but on how they define an investment idea.
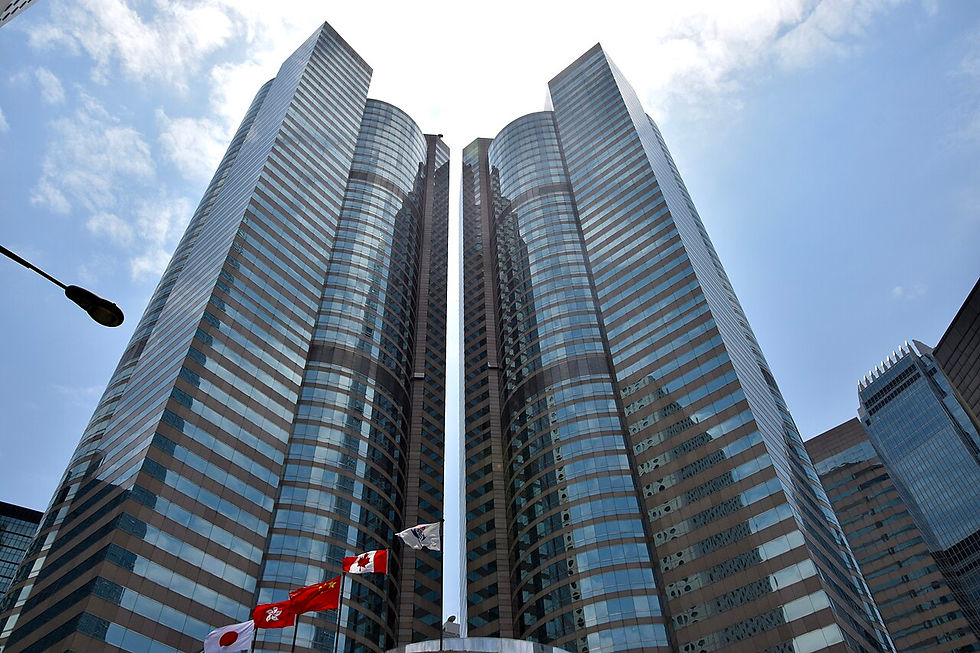
Exchange Square in Central, where Hong Kong’s expanding ETF market is competing for investor attention. Image: Ank Kumar / CC BY-SA 4.0
ChinaAMC’s HALO product is one example. According to index provider Solactive, the underlying strategy selects 60 Hong Kong and U.S. companies described as “heavy assets, low obsolescence.” The index uses geographic and sector limits and is rebalanced twice a year. The concept is meant to identify established businesses whose physical or strategic assets may retain value, but the label should not be confused with a guarantee of durability.
Other products lean into themes that have dominated investor attention. Artificial intelligence funds can package chipmakers, software companies, infrastructure providers and users of AI into a single trade. Healthcare funds offer a different structural argument built around demographics, innovation and demand. High-dividend strategies appeal to investors seeking cash distributions, though a high historical yield can also reflect a falling share price or a challenged business.
The launches reinforce Hong Kong’s role as a bridge between mainland Chinese asset managers and international capital. Fund groups can list strategies in multiple currency classes, reach investors familiar with Hong Kong’s market infrastructure and build products around both regional and global securities. Hong Kong remains one point in a three-city financial network, but its ETF expansion gives it a distinctive channel for packaged exposure to Chinese and cross-market themes.
For investors, the product name is only the beginning of the research. Two funds that both use “AI” can hold very different companies, apply different screens and carry different concentrations. The index methodology, portfolio disclosure, total expense ratio, trading spread, fund size and market-maker activity all affect the experience. A compelling theme can still be a poor instrument if liquidity is thin or costs are high.
Currency deserves equal attention. A fund may trade in Hong Kong dollars, renminbi or U.S. dollars while holding assets that earn revenue in several currencies. The trading currency does not automatically remove the economic exposure beneath the portfolio. Investors should read the prospectus and product key facts statement to understand hedging, distribution policy and how foreign-exchange movements can affect returns.
The listing wave also raises a question about timing. Asset managers tend to launch products when a narrative is already easy to explain, which can coincide with elevated valuations. Artificial intelligence, defensive income and healthcare each have credible long-term cases, but popularity can compress future returns if investors pay too much. Diversification within an ETF does not protect against every company being exposed to the same crowded assumption.
For Hong Kong’s market, however, the broader trend is constructive. More issuers and strategies can deepen trading, improve price competition and give investors alternatives to traditional broad-market funds. The test will be whether these launches accumulate durable assets and active secondary-market liquidity after the opening campaign. Products that remain small can eventually face wider spreads, weak trading or closure.
September 30 therefore marks more than a busy listing day. It shows Hong Kong’s ETF market moving from simple access products toward increasingly specific narratives. That creates choice, but it transfers more responsibility to investors. The strongest question is not which theme sounds most exciting; it is whether the rules, holdings, costs and risks of the fund provide a sensible way to express a view that an investor can defend after the launch-day attention fades.


Comments