Bank of England Holds Rates as Inflation Risks Revive Talk of a Hike

LONDON — The Bank of England has kept Bank Rate unchanged, but the decision carried a sharper warning than a routine hold. The Monetary Policy Committee voted 6–3 to maintain the benchmark, with three members preferring a quarter-point increase. That split pushed the possibility of another rise back into business planning after months in which the central question had been how quickly borrowing costs might fall.
The division reflects an economy pulled in opposite directions. Growth remains uneven and households still feel the cumulative effect of expensive mortgages, rent and credit. At the same time, energy costs and persistent domestic price pressure threaten to keep inflation above the Bank's 2 percent target. Policymakers must decide whether those pressures will fade or become embedded in wages and services before acting.

Governor Andrew Bailey emphasized uncertainty, particularly around energy prices. A temporary shock does not always justify tighter monetary policy, because higher rates cannot produce oil or gas. The danger is that an external increase changes expectations, wage bargaining and business pricing. Once that happens, an imported cost can become a domestic inflation problem that lasts after the original shock subsides.
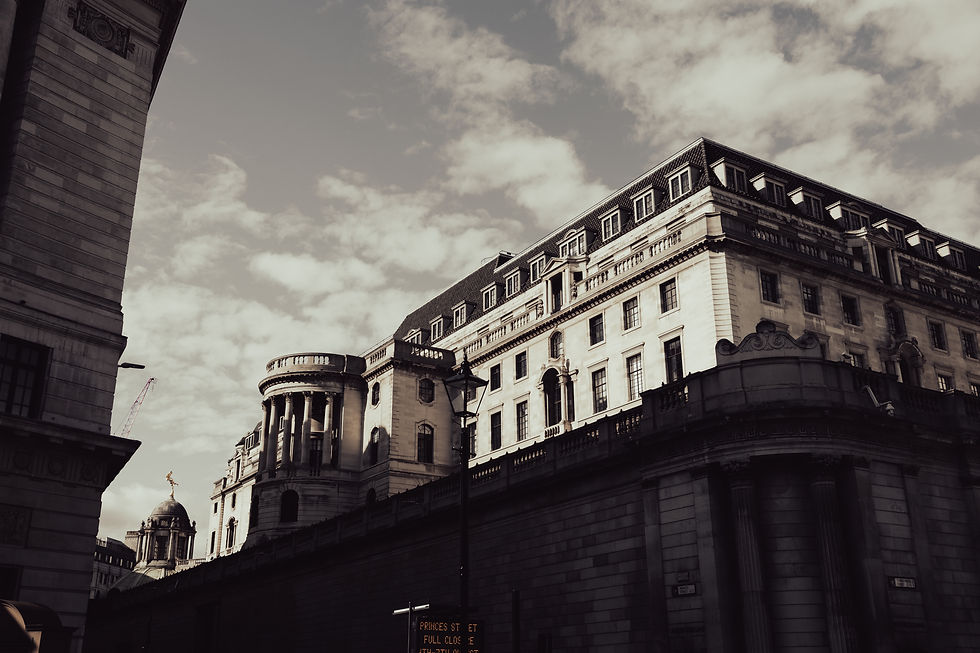
For the City of London, the vote matters as much as the headline decision. A 6–3 split tells investors that support for a hike is no longer marginal. Bond yields, sterling and bank shares respond to the expected path of policy rather than only today's rate. If incoming data show stronger pay growth or stubborn services inflation, a majority could form sooner than businesses assumed.
Borrowers face a less dramatic but equally important adjustment. Many households refinance fixed-rate mortgages in stages, so the economy feels monetary policy with a delay. Recent UK mortgage lending data showed activity recovering while high loan-to-value borrowing reached its largest share in years. That combination makes the outlook sensitive: stronger demand can support housing, but heavily leveraged buyers have less room for another rise in monthly payments.
Companies must also revisit financing assumptions. A business that expected steady cuts may have postponed refinancing or investment while waiting for cheaper credit. The latest vote weakens confidence in that strategy. Firms do not need to predict the next meeting perfectly, but they do need to test budgets against higher interest expense, volatile energy bills and softer consumer demand arriving at the same time.
The Bank's challenge is communication. If officials sound too relaxed, markets may loosen financial conditions and add to inflation. If they sound too aggressive, they may tighten credit before the evidence justifies it. Holding rates while revealing meaningful support for an increase allows the committee to preserve flexibility, though it also leaves households and investors parsing every speech for a timetable that does not yet exist.
Britain's stronger July growth gives policymakers slightly more room to focus on inflation, but one good month does not settle the trend. Services can expand while manufacturing or consumer-facing sectors struggle. The committee will need several releases on employment, wages, activity and prices to distinguish resilience from noise. A rate rise based on a temporary burst would carry costs; waiting too long against persistent inflation would carry different ones.
International conditions add another layer. The Federal Reserve and European Central Bank influence global funding, exchange rates and investor appetite, but the Bank of England cannot simply follow either institution. Britain's energy exposure, wage structure and mortgage market create a distinct transmission mechanism. London businesses with dollar or euro revenue may experience the decision through currencies before they feel it through domestic loans.
The September hold is best understood as a pause with active disagreement, not an all-clear. The next move will depend on whether inflation risks broaden beyond energy and whether demand can absorb tighter policy. For companies and households, the practical lesson is to stop treating lower rates as a scheduled event. The Bank has left the door open in both directions, and the cost of money in Britain is once again a live decision rather than a predictable descent.

Comments