London Fund Managers Face a Turning Point in the FCA’s Rulebook Rewrite

London’s alternative-investment industry is entering a decisive stretch in the Financial Conduct Authority’s proposed rewrite of the rules governing fund managers. The regulator is holding a prudential roundtable at its Canary Wharf office on September 14 as it gathers feedback on a plan that would replace a complex inherited framework with a graduated system for small, medium and large firms.
The consultation matters well beyond compliance departments. The FCA says UK managers oversee almost £2 trillion in alternative assets and more than £16 trillion across asset management, making the country the world’s second-largest market. London’s ability to attract funds, investors and specialist talent therefore depends partly on whether regulation can remain credible without imposing the same operational burden on every firm.
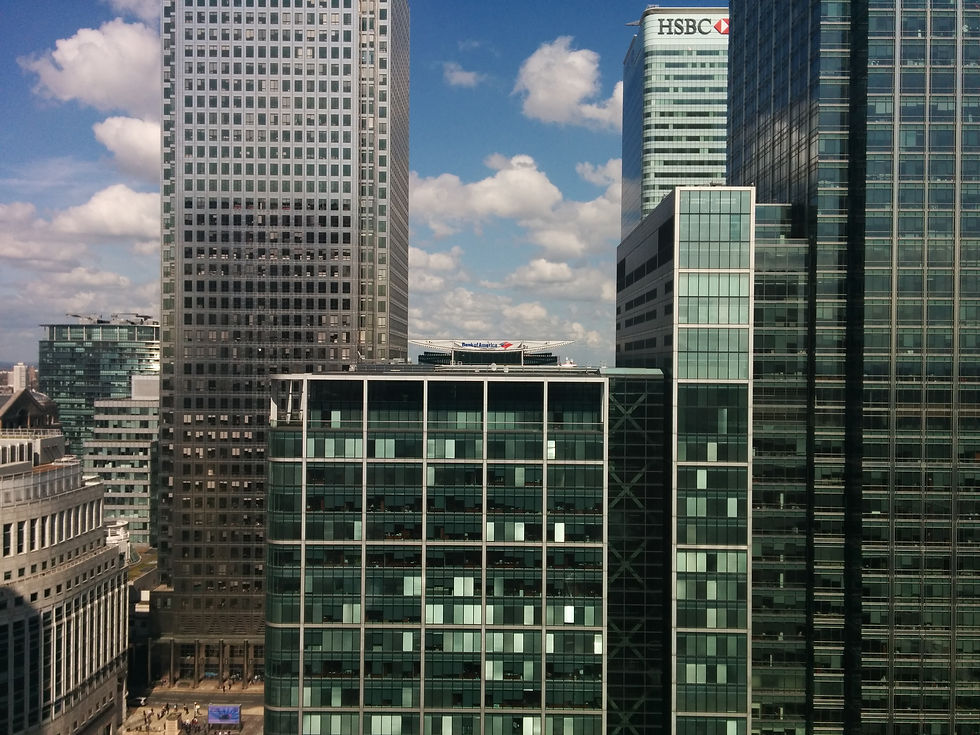
The Canary Wharf skyline in London. Photo: Salimfadhley / CC BY-SA 3.0. Display size adjusted.
Under the proposal, the current approach would give way to three size-based tiers with rules applied according to a manager’s scale and activities. The FCA also wants a dedicated Alternative Investment Funds sourcebook, known as ALTS, to bring most requirements together. The goal is a framework that is easier to enter, navigate and update while retaining safeguards for investors and market integrity.
The existing regime is rooted in the European Union’s Alternative Investment Fund Managers Directive, which was retained in UK law after Brexit. The FCA argues that requirements are now spread across legislation, Treasury regulations and its own handbook, and that some thresholds have not kept pace with inflation or market growth. It also says the framework can treat very different strategies too similarly.
That distinction matters because a hedge fund trading liquid instruments can present different risks from a private-equity or real-asset fund holding investments for years. A proportionate rulebook could reduce unnecessary work for smaller managers while reserving heavier expectations for businesses with greater scale or complexity. The challenge is ensuring that proportionality does not become a route around essential governance, liquidity controls or investor protection.
The FCA has linked this consultation to separate proposals on fund reporting and remuneration. Together, the changes are intended to modernize the operating environment for asset managers rather than adjust one isolated rule. Independent legal analyses from Norton Rose Fulbright and Practical Law have emphasized the breadth of the package and the need for firms to examine how the new tiers and reporting obligations would affect them.
For London firms, implementation is not immediate. The FCA says the new regime is currently envisaged for 2028, and the Treasury is running a parallel consultation on changes to the underlying legislation. Most discussion chapters close on September 18, while responses to the consultation paper and prudential discussion chapter are due October 22 after the regulator extended that deadline.
Those dates give managers time to model the effect of new thresholds, staffing expectations and systems work. They also create a test of the government’s wider effort to improve the City’s competitiveness. A simpler handbook may reduce legal and administrative costs, but firms will judge the reform by the final rules, transition period and consistency of supervision rather than by the promise of simplification alone.
The proposal could matter to firms outside London as well, because many overseas managers market funds into the United Kingdom or delegate work to British businesses. Clearer rules may support cross-border activity, but only if international groups can determine quickly which obligations apply. Alignment with other major markets will remain a commercial consideration even when the UK chooses a distinct framework.
Investors have a stake in that balance. Alternative funds can involve complex strategies, illiquid holdings and leverage, making robust oversight important even when clients are sophisticated. If the tiers match obligations more closely to actual risk, the reform could improve clarity without weakening standards. If boundaries are poorly drawn, similar firms could face different burdens or incentives to remain artificially below a threshold.
The September 14 London roundtable is one step in a longer rulemaking process, not a final decision. The next signals will come from consultation responses, Treasury legislation and the FCA’s eventual policy statement. For the City, the central question is whether the United Kingdom can turn post-Brexit flexibility into a rulebook that is both easier to use and strong enough to sustain international confidence.
Related coverage: Hong Kong Finance Jobs Draw Returning Talent as Fundraising Rebounds, LondonMetric's £105 Million Property Reset Shifts Capital Toward Higher-Yield Assets and Headlam Moves Toward Administration as Its London Listing Is Suspended.

Comments